Should I Buy a House Now or Wait Until 2026? Financial Readiness and Housing Market Trends
Table of Contents
- Financial Readiness for Homeownership
- Essential Expenses to Consider When Budgeting for a Mortgage
- Importance of Emergency Funds and Ideal Down Payment Amount
- Credit Scores and Mortgage Rates
- Mortgage Options and Their Implications for Homebuyers in 2026
- Fixed-Rate vs Adjustable-Rate Mortgages
- Government-Backed Loans
- Cash-Out Refinancing, Should i buy a house now or wait until 2026
- Housing Supply Chain Challenges and Their Potential Impact on Homebuyers
- Causes of Land Price Increases
- Effect of Supply Chain Disruptions on Home Construction
- Shadow Inventory and Its Impact on Home Prices
- Final Thoughts
- Clarifying Questions: Should I Buy A House Now Or Wait Until 2026
Should I Buy a House Now or Wait Until 2026 unfolds like a financial puzzle, where several factors intersect and influence the ultimate decision. The housing market trends, financial readiness, and mortgage options all play crucial roles in determining whether homeownership is the right fit for you.
The US housing market in 2024 is marked by rising interest rates and increasing home prices, making it crucial for homebuyers to assess their financial readiness and consider all available mortgage options. Understanding the impact of inflation on housing markets and exploring the differences between fixed-rate and adjustable-rate mortgages are just a few essential components of this puzzle.
Financial Readiness for Homeownership

When considering purchasing a home, financial readiness is a critical aspect to assess. It involves evaluating your income, expenses, savings, and creditworthiness to determine if you can afford a mortgage, closing costs, and ongoing homeownership expenses. In this section, we will delve into the essential expenses homeowners must consider when budgeting for a mortgage, discuss the importance of emergency funds and the ideal amount for a down payment, and explore the concept of credit scores and their influence on mortgage rates.
Essential Expenses to Consider When Budgeting for a Mortgage
When budgeting for a mortgage, homeowners must consider several essential expenses that may not be immediately apparent. These expenses include:
- Paying property taxes annually or through monthly escrow payments
- Insurance premiums for homeowners' insurance, flood insurance, and earthquake insurance
- Property maintenance and repairs, such as replacing a roof or fixing a plumbing issue
- Homeowners association (HOA) fees, if applicable
- Utility bills, including electricity, water, gas, and trash removal
- Mortgage insurance, required for homeowners with less than 20% down payment
These expenses can add up quickly, and homeowners must factor them into their monthly mortgage payment to avoid financial surprises down the line. As a general guideline, homeowners should aim to spend no more than 30% of their gross income on housing costs, including mortgage payments, property taxes, and insurance.
Importance of Emergency Funds and Ideal Down Payment Amount
Emergencies can arise at any time, and homeowners must be prepared to cover unexpected expenses, such as a job loss or medical crisis. An emergency fund can provide a financial cushion in these situations, allowing homeowners to stay on top of their mortgage payments and avoid foreclosure. It is generally recommended that homeowners save 3-6 months' worth of living expenses in an easily accessible savings account.
As for the ideal down payment amount, it varies depending on individual circumstances. However, making a significant down payment (20% or more) can save homeowners thousands of dollars in mortgage insurance premiums over the life of the loan. For example, if a homeowner puts down 20% on a $500,000 home, they can avoid paying mortgage insurance premiums, which can amount to $1,000-$2,000 per year.
Credit Scores and Mortgage Rates
Credit scores play a significant role in determining mortgage rates and terms. Lenders use credit scores to assess an individual's creditworthiness and calculate the risk of lending them money. The most widely used credit scoring model is the FICO scoring model, which ranges from 300 to 850. Here's a breakdown of FICO credit score ranges and their corresponding mortgage rates:| FICO Credit Score | Mortgage Rate |
|---|---|
| 720-850 | 4.0%-4.5% |
| 680-719 | 4.5%-5.0% |
| 620-679 | 5.0%-6.0% |
| 580-619 | 6.0%-7.0% |
| 500-579 | 7.0%-8.0% |
Mortgage Options and Their Implications for Homebuyers in 2026

Mortgages can be broadly categorized into two types: fixed-rate and adjustable-rate mortgages.
Fixed-Rate vs Adjustable-Rate Mortgages
| Fixed-Rate Mortgage | Adjustable-Rate Mortgage |
|---|---|
| The interest rate remains the same for the entire loan term. | The interest rate can change based on market fluctuations. |
| The monthly payment remains the same throughout the loan term. | The monthly payment can increase or decrease when the interest rate changes. |
| Often offered with longer loan terms (15-30 years). | Typically offered with shorter loan terms (5-10 years). |
| May have higher upfront costs. | May have lower upfront costs. |
Government-Backed Loans
The Federal Housing Administration (FHA) and the Department of Veterans Affairs (VA) offer government-backed loans that provide more lenient credit score requirements and lower down payment options.- FHA Loans: These loans require a minimum credit score of 580 and a down payment as low as 3.5%. They also offer more lenient debt-to-income ratio requirements.
- VA Loans: These loans require no down payment and offer more lenient credit score requirements. They also offer lower mortgage insurance premiums.
Cash-Out Refinancing, Should i buy a house now or wait until 2026
Cash-out refinancing allows homeowners to tap into the equity in their home by refinancing their mortgage and borrowing a larger amount than the current mortgage balance.Cash-out refinancing can be a viable option for homeowners who need to access a large amount of cash, such as for home repairs or debt consolidation.However, cash-out refinancing can also lead to higher monthly payments and increased debt. It is essential to consider the potential risks and benefits before deciding to pursue cash-out refinancing.
Housing Supply Chain Challenges and Their Potential Impact on Homebuyers
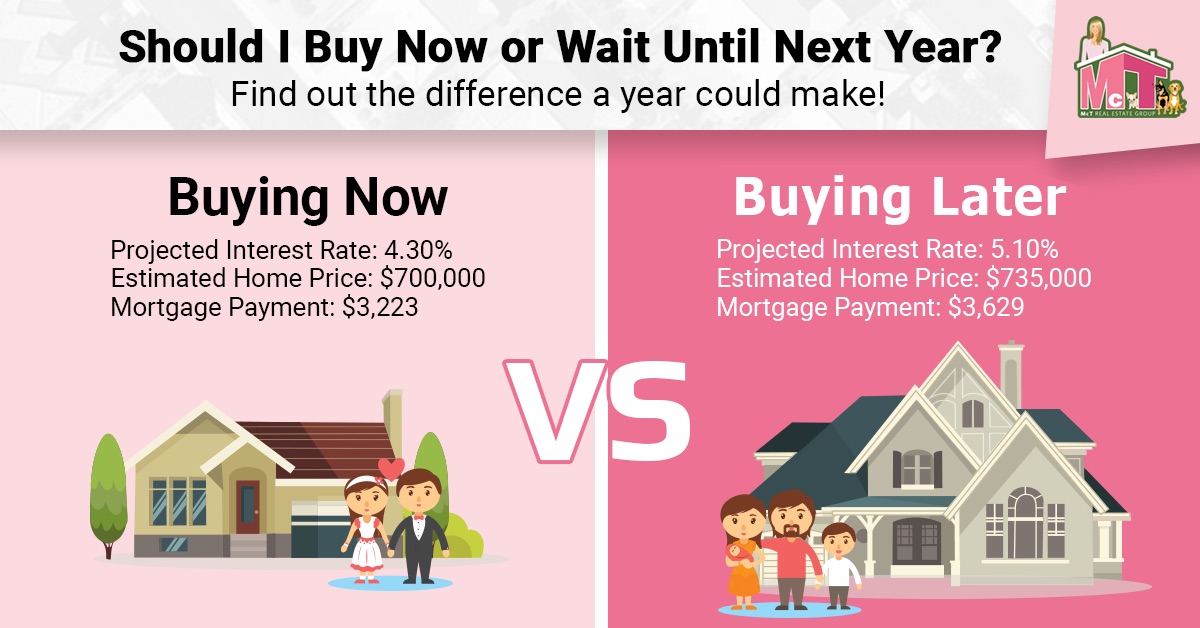
Housing supply shortages have been a persistent issue in many parts of the world, driven by a combination of factors, including high land prices and stringent environmental regulations. These regulations aim to protect natural habitats and wildlife, but they can limit the availability of land for development. The high cost of land acquisition has led to increased construction costs, making it more challenging for builders to complete projects within budget.
Causes of Land Price Increases
- The rising demand for housing in areas with excellent infrastructure, schools, and access to employment opportunities has driven up land prices in these areas.
- The limited availability of land in desirable locations has created a seller's market, allowing developers to charge higher prices for the same piece of land.
- The cost of acquiring and developing land has increased due to the need for environmental impact assessments, permitting, and other regulatory requirements.
Effect of Supply Chain Disruptions on Home Construction
Supply chain disruptions have become a common occurrence in the construction industry, impacting the timely delivery of materials and equipment. These disruptions can be caused by various factors, including:- Demand and supply imbalances: Sudden increases in demand for materials and equipment can lead to shortages and delays.
- Transportation and logistics: Disruptions to transportation networks, such as road closures or port strikes, can hinder the delivery of materials and equipment.
- Supplier capacity: Insufficient supplier capacity can lead to delays in delivering materials and equipment, impacting construction timelines.
Shadow Inventory and Its Impact on Home Prices
Shadow inventory refers to homes that are not currently on the market but are likely to be sold or rented in the near future. This can include:- Banks and hedge funds holding foreclosed homes off the market. li>Builders holding inventory of unsold homes.
Final Thoughts
Ultimately, the decision to buy a house now or wait until 2026 depends on a combination of individual financial readiness, mortgage options, and housing market trends. By carefully considering these factors and seeking guidance from financial experts, homebuyers can make an informed decision that meets their unique needs and financial goals.
Clarifying Questions: Should I Buy A House Now Or Wait Until 2026
What are the key factors to consider when deciding whether to buy a house now or wait until 2026?
The key factors to consider include current housing market trends, individual financial readiness, mortgage options, and local economic conditions. It's essential to assess these factors carefully and seek guidance from financial experts to make an informed decision.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of gifellowcasesubmission.olympusamerica.com.