How Much to Put Down on a House to Secure Your Mortgage and Future
Table of Contents
- Understanding the Importance of Down Payment in Mortgage Finance
- Examples of Different Down Payment Scenarios
- Factors Influencing the Optimal Down Payment Amount
- Credit Score and Optimal Down Payment Amount
- Income and Optimal Down Payment Amount
- Debt-to-Income Ratio and Optimal Down Payment Amount
- Property Type and Optimal Down Payment Amount
- Location and Optimal Down Payment Amount
- Interest Rates and Optimal Down Payment Amount
- Personal Financial Goals and Optimal Down Payment Amount
- Creating a Down Payment Budget and Savings Plan
- Step 1: Set Financial Goals
- Step 2: Track Expenses
- Step 3: Create a Savings Plan
- Step 4: Consider Emergency Funds and Other Financial Priorities, How much to put down on a house
- Understanding Down Payment Assistance Programs and Options
- Types of Down Payment Assistance Programs
- HUD Good Neighbor Next Door Program
- FHA Down Payment Grant
- Veterans Affairs (VA) Home Loan Guaranty Program
- USDA Rural Development Guaranteed Loan Program
- State and Local Down Payment Assistance Programs
- Difference Between Down Payment Gifts and Assistance Programs
- Source of Funds
- Eligibility Requirements
- Benefits
- Restrictions
- Pros and Cons of Using Down Payment Assistance and Alternative Financing Options
- Pros
- Cons
- The Impact of Down Payment on Home Equity and Long-Term Wealth: How Much To Put Down On A House
- Long-Term Wealth Implications
- Comparing Down Payment Strategies
- Real-Life Scenario: Retirement Savings and Financial Security
- Tax Benefits and Incentives for Down Payment Savings
- Understanding Tax-Advantaged Accounts
- Tax Credits and Deductions for Homebuyers
- Carefully Consider Tax Implications
- Outcome Summary
- Popular Questions
How much to put down on a house sets the stage for this crucial financial decision, offering readers a clear understanding of the process and the importance of down payment in mortgage finance. The down payment significantly affects the mortgage interest rate, and making a larger down payment can provide numerous benefits.
The benefits of making a larger down payment include lower mortgage insurance premiums, reduced debt-to-income ratio, and increased equity in the home. A larger down payment can also lead to lower monthly mortgage payments and a lower risk of defaulting on the loan. However, it's essential to consider the pros and cons of different down payment scenarios and their financial implications.
Understanding the Importance of Down Payment in Mortgage Finance
In Batak society, where saving and prudent financial planning are highly valued, understanding the significance of down payment in mortgage finance is crucial for prospective homeowners. A down payment is a portion of the purchase price of a house paid at the time of closing, which can have a significant impact on the monthly mortgage payments, interest rates, and overall housing costs. The amount of down payment can affect the amount borrowed, interest rate, and mortgage repayment period, making it an essential aspect of mortgage finance.
A down payment affects the mortgage interest rate in several ways. Firstly, a larger down payment results in a smaller loan amount, which typically leads to a lower interest rate. This is because the lender views the borrower as less risky, as they have invested a larger portion of their own money in the property. This, in turn, can lead to lower monthly mortgage payments. For example, assume a property costs IDR 500,000,000 (Indonesian Rupiah) and a borrower makes a down payment of 30% (IDR 150,000,000) and borrows the remaining IDR 350,000,000. In this scenario, the lender views the borrower as less risky due to the larger down payment, which can lead to a lower interest rate compared to someone who puts down a smaller amount.
### Benefits of Making a Larger Down Payment
A larger down payment can have several benefits, including:
- Paying less in interest over time: By making a larger down payment, borrowers can reduce the amount of interest paid over the life of the loan.
- Lower monthly mortgage payments: A smaller loan amount results in lower monthly payments, making it more manageable for borrowers.
- Reducing the need for private mortgage insurance (PMI): Some lenders require PMI for borrowers who put down less than 20% of the purchase price. A larger down payment can waive this requirement.
- Improving credit score: Making timely mortgage payments, which is easier with lower monthly payments, can help improve credit scores.
Examples of Different Down Payment Scenarios
Here are a few examples of different down payment scenarios and their financial implications:
| Down Payment | Interest Rate | Monthly Mortgage Payment |
|---|---|---|
| IDR 150,000,000 (30% down payment) | 6% interest rate | IDR 2,500,000 per month |
| IDR 100,000,000 (20% down payment) | 6% interest rate | IDR 2,800,000 per month |
| IDR 50,000,000 (10% down payment) | 7% interest rate (due to higher risk) | IDR 3,200,000 per month |
A larger down payment can also provide peace of mind for borrowers, as they have more invested in the property and are less likely to be at risk of default. In Batak culture, where family and community ties are strong, this stability can bring a sense of security and contentment to homeowners.
Factors Influencing the Optimal Down Payment Amount
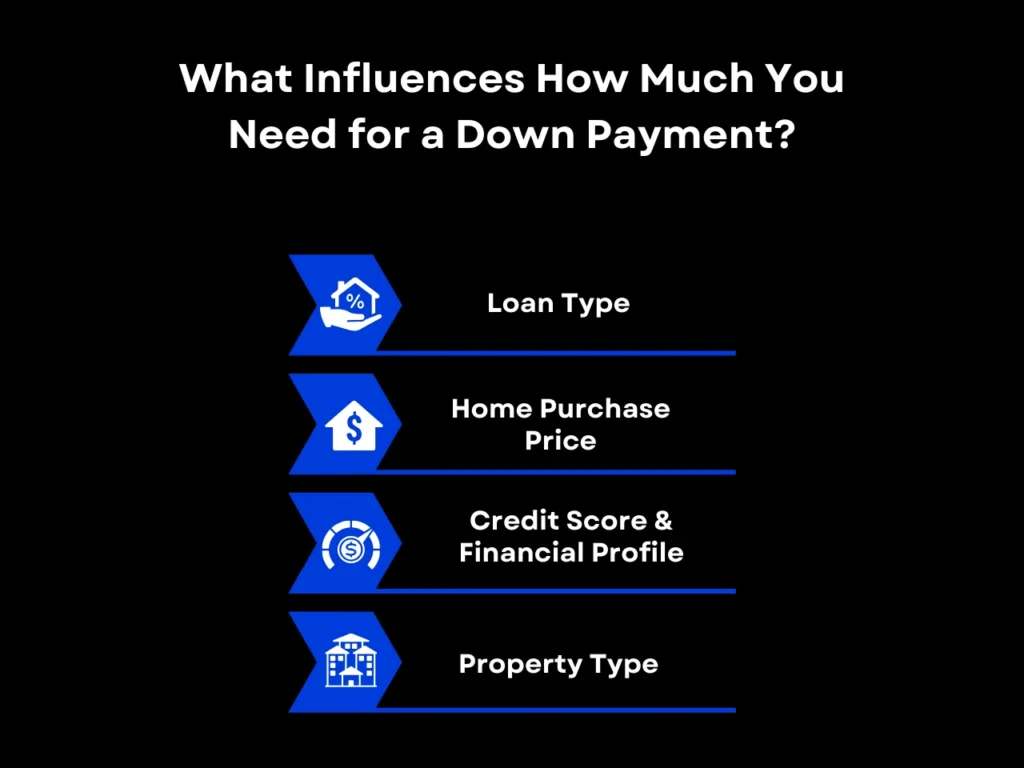
Your down payment decision should carefully consider a range of factors, each having a significant impact on the outcome. It's crucial that you weigh these elements to determine the optimal down payment amount for your personal financial situation. In this section, we will explore crucial factors that influence your down payment decision, including credit score, income, debt-to-income ratio, property type, location, interest rates, and personal financial goals.Credit Score and Optimal Down Payment Amount
A strong credit score plays a significant role in determining the ideal down payment. It significantly affects the interest rate you will qualify for and can even affect loan approval. A higher credit score can result in more favorable terms, including lower interest rates and more flexible down payment options. Conversely, a lower credit score may necessitate a higher down payment or even lead to loan rejection. Therefore, before making any decisions, always check your credit report and work to improve your credit score.- Typically, lenders prefer credit scores of 700 or above to qualify for the best interest rates and down payment options.
- A credit score above 720 can help you qualify for an FHA loan with as little as 3.5% down payment.
- However, credit scores between 580-679 might be eligible for FHA loans but with higher down payments.
Income and Optimal Down Payment Amount
Your income is another essential factor in determining the ideal down payment amount. Your gross income determines your ability to qualify for a loan. Additionally, it affects the debt-to-income ratio, which is a crucial metric in lending. The more stable your income, the more likely it is that you'll qualify for lower down payments and better loan terms. Conversely, irregular income may necessitate a larger down payment or even impact your likelihood of loan approval.- A stable income can qualify you for as little as 3.5% down payment with FHA loans.
- Lenders like Fannie Mae and Freddie Mac often require 5% to 10% down payment for conventional loans.
- However, for non-traditional income sources, lenders may require higher down payments, such as 15% to 20%.
Debt-to-Income Ratio and Optimal Down Payment Amount
Your debt-to-income ratio is an essential factor in determining your down payment. This ratio compares your monthly debt payments to your gross income. A higher debt-to-income ratio may necessitate a higher down payment or even impact your likelihood of loan approval. It is also vital to consider that other debt sources, such as auto loans, credit cards, and student loans, can also affect your debt-to-income ratio. Aim to keep your debt-to-income ratio below 36% to have better options.- A debt-to-income ratio below 36% typically qualifies you for lower down payments with conventional loans.
- However, FHA loans may be more lenient, allowing for debt-to-income ratios up to 31% to 45%.
- For debt-to-income ratios above 43%, lenders may require 20% to 30% down payment or even reject the loan application.
Property Type and Optimal Down Payment Amount
The type of property you're interested in purchasing can influence your down payment decision. Different types of properties often require different down payments. Typically, down payments for single-family homes are lower than those for condominiums or townhouses, while mobile homes or manufactured homes can have very low or no down payments at all.- Typically, single-family homes have down payments ranging from 3.5% to 20%.
- Condominiums and townhouses usually require down payments of 5% to 20%.
- Mobile homes or manufactured homes may have down payments of less than 1% to 5%.
Location and Optimal Down Payment Amount
The location of your desired property is also an essential factor in determining the optimal down payment amount. In some neighborhoods or areas with high demand or low inventory, down payments may be higher due to competitive market conditions.- High-demand neighborhoods may have down payments ranging from 10% to 30%.
- Low-demand areas with high inventory may have down payments of 3.5% to 10%.
Interest Rates and Optimal Down Payment Amount
Interest rates also influence the ideal down payment amount. With interest rates rising or falling, lenders may re-evaluate their down payment requirements. Typically, you may qualify for lower interest rates with a higher down payment. Conversely, if you're willing to accept a higher interest rate, you may qualify for lower down payments.- A down payment of 20% can secure a better interest rate, typically between 4% and 6%.
- A down payment of 10% to 20% can qualify you for a mid-tier interest rate between 4.25% and 7%.
- However, with a down payment of 5% to 10%, you may face lower interest rates between 5% and 7.5%.
Personal Financial Goals and Optimal Down Payment Amount
Your personal financial goals and risk tolerance ultimately decide the ideal down payment amount. If you prioritize long-term financial stability and risk aversion, you may aim for a higher down payment, such as 20%. Alternatively, if you're more willing to take on risks for potential higher returns, you might opt for a lower down payment, around 5%.- A down payment of 20% typically offers greater financial security and more favorable terms.
- A down payment of 5% to 10% might be suitable for those willing to take on more financial risk.
Creating a Down Payment Budget and Savings Plan
To save for a down payment on a house, it is crucial to create a budget and savings plan. This plan will help you understand how much you need to save, how you can save it, and when you can achieve your goal. Here's a step-by-step guide to help you create a down payment budget and savings plan.Step 1: Set Financial Goals
The first step in creating a down payment budget and savings plan is to set a specific goal. This goal should include not only the target amount but also the timeline for reaching it. For example, you might set a goal to save $20,000 for a down payment in 12 months. Having a clear goal will help you stay focused and motivated throughout the savings process.| Current Savings | Monthly Contributions | Projected Savings | Estimated Time to Save |
|---|---|---|---|
| Initial Savings Amount | Monthly Savings Amount | Total Savings after 12 months | 12 months |
Step 2: Track Expenses
Tracking your expenses is essential to understand where your money is going and identify areas where you can cut back. You can use a spreadsheet or an app to track your expenses. Make sure to include all your income sources and expenses, no matter how small they may seem.Step 3: Create a Savings Plan
Based on your financial goal and expense tracking, create a savings plan. Allocate a specific amount from your income each month towards your down payment savings. You may want to consider setting up automatic transfers from your checking account to your savings account to make saving easier and less prone to being neglected.Step 4: Consider Emergency Funds and Other Financial Priorities, How much to put down on a house
When saving for a down payment, it's essential to consider other financial priorities, such as emergency funds, retirement savings, and high-interest debt repayment. Allocate a portion of your income towards these priorities, but prioritize your down payment savings to achieve your goal."It's essential to strike a balance between saving for short-term goals, like a down payment, and long-term goals, like retirement." - Financial Expert
Understanding Down Payment Assistance Programs and Options
Down payment assistance programs and options play a vital role in making homeownership a reality for many individuals and families. These programs provide financial assistance to help with the down payment, closing costs, and other expenses associated with purchasing a home.There are numerous down payment assistance programs available, each with its own set of eligibility requirements and benefits. Understanding these programs can help prospective homebuyers make informed decisions about their mortgage financing options.
Types of Down Payment Assistance Programs
There are several types of down payment assistance programs available, including:- Grants: These are free government programs that provide financial assistance to homebuyers in the form of a grant.
- Second Mortgages: These are additional loans that are secured by the property and used to finance the down payment.
- Closing Cost Assistance: These programs provide financial assistance for closing costs, inspection fees, and other expenses associated with purchasing a home.
- Income-Based Programs: These programs provide financial assistance based on the borrower's income and can be used in conjunction with other down payment assistance programs.
- First-Time Homebuyer Programs: These programs provide financial assistance to first-time homebuyers, including down payment assistance and closing cost assistance.
HUD Good Neighbor Next Door Program
HUD Good Neighbor Next Door is a program that provides financial assistance to teachers, police officers, firefighters, and other public servants who are interested in buying a home in a HUD-owned property.
- Eligibility: Must be a teacher, police officer, firefighter, or other public servant; must purchase a HUD-owned property in a designated area.
- Benefits: 50% discount on the purchase price; closing cost assistance; and no down payment required.
FHA Down Payment Grant
The FHA Down Payment Grant program provides financial assistance to low-income homebuyers who are purchasing a home in a designated area.
- Eligibility: Must be a low-income homebuyer; must purchase a home in a designated area; and must be eligible for an FHA mortgage.
- Benefits: Up to $10,000 in financial assistance; 3.5% down payment required; and no closing costs associated with the assistance.
Veterans Affairs (VA) Home Loan Guaranty Program
The VA Home Loan Guaranty Program provides financial assistance to veterans, active-duty military personnel, and surviving spouses who are purchasing a home.
- Eligibility: Must be a veteran, active-duty military personnel, or surviving spouse; must purchase a home with a VA-approved lender; and must be eligible for a VA mortgage.
- Benefits: No down payment required; no mortgage insurance required; and closing cost assistance available.
USDA Rural Development Guaranteed Loan Program
The USDA Rural Development Guaranteed Loan Program provides financial assistance to homebuyers who are purchasing a home in a rural area.
- Eligibility: Must be purchasing a home in a rural area; must meet income and credit requirements; and must be eligible for a USDA mortgage.
- Benefits: No down payment required; no mortgage insurance required; and closing cost assistance available.
State and Local Down Payment Assistance Programs
There are numerous state and local down payment assistance programs available, including the California Homebuyer's Downpayment Assistance Program and the Illinois Downpayment Assistance Program.
- Eligibility: Varies by program; must meet income and credit requirements; and must be eligible for a mortgage.
- Benefits: Up to 10% of the purchase price in financial assistance; 3.5% down payment required; and closing cost assistance available.
Difference Between Down Payment Gifts and Assistance Programs
There is a significant difference between down payment gifts and assistance programs. Down payment gifts are funds provided by a third party, such as a family member or friend, to help with the down payment. Down payment assistance programs, on the other hand, are government- or non-profit-funded programs that provide financial assistance to help with the down payment.The key differences between down payment gifts and assistance programs are:
Source of Funds
Down payment gifts come from a third party, while down payment assistance programs come from government or non-profit organizations.
Eligibility Requirements
Down payment gifts typically do not have eligibility requirements, while down payment assistance programs have strict eligibility requirements, including income and credit requirements.
Benefits
Down payment gifts do not provide any additional benefits, while down payment assistance programs often provide additional benefits, such as closing cost assistance and no mortgage insurance required.
Restrictions
Down payment assistance programs often have restrictions on the amount of assistance provided and the type of home that can be purchased.
Pros and Cons of Using Down Payment Assistance and Alternative Financing Options
Using down payment assistance and alternative financing options can be beneficial for homebuyers who are struggling to come up with a down payment. However, there are also some potential drawbacks to consider.Pros
Down payment assistance and alternative financing options can help homebuyers overcome the hurdle of saving for a down payment; They can provide a lower monthly mortgage payment, as the borrower is not required to make a large down payment; They can provide access to homeownership for those who may not have been able to qualify for a mortgage otherwise.
Cons
Down payment assistance and alternative financing options can have higher interest rates and fees compared to traditional financing options; They can require a higher credit score, which may be a challenge for some borrowers; They can have stricter eligibility requirements, which may limit the number of borrowers who can qualify.
The Impact of Down Payment on Home Equity and Long-Term Wealth: How Much To Put Down On A House
When it comes to buying a home, the amount of down payment made plays a significant role in determining the equity and long-term wealth of the homeowner. A higher down payment can lead to greater equity in the property, reducing the need for future mortgage payments and ultimately increasing the owner's net worth.The equation for calculating the home equity is as follows: Home Equity = Down Payment + (Mortgage Payments - Interest Paid). This shows that the higher the down payment, the higher the home equity. However, the impact of down payment on long-term wealth is more complex and depends on several factors, including the loan term, interest rate, and property appreciation.
Long-Term Wealth Implications
A study by the National Association of Realtors found that homeowners who put down 20% or more of the home's purchase price tend to accumulate more wealth over time compared to those who make lower down payments. This is because homeowners with higher down payments have lower mortgage balances and can potentially benefit from equity growth and property appreciation.
For instance, let's consider two scenarios: one where the homeowner puts down $100,000 on a $500,000 home, and another where the homeowner puts down $20,000 on the same home. Assuming the same loan term and interest rate, the homeowner with a 20% down payment will have lower monthly mortgage payments and can potentially accumulate more wealth over time.
A higher down payment not only reduces the need for future mortgage payments but also increases the equity in the property, which can lead to greater long-term wealth.
Comparing Down Payment Strategies
Different down payment strategies can affect the long-term wealth of homeowners in various ways. For example, making a larger down payment can reduce the need for future mortgage payments and increase the equity in the property. However, it may also limit the homeowner's liquidity and ability to access funds for other financial goals or emergencies.
In contrast, making a lower down payment may result in higher monthly mortgage payments, which can increase the homeowner's debt-to-equity ratio and potentially reduce their net worth. However, it may also provide more liquidity and access to funds for other financial goals or emergencies.
- Higher Down Payment Strategy: Lower Mortgage Payments, Higher Equity Growth, Higher Long-Term Wealth
- Lower Down Payment Strategy: Higher Mortgage Payments, Lower Equity Growth, Lower Long-Term Wealth
Real-Life Scenario: Retirement Savings and Financial Security
Consider a scenario where a homeowner puts down 20% on a $500,000 home, compared to another homeowner who puts down 10%. Assuming the same loan term and interest rate, the homeowner with a 20% down payment will have lower monthly mortgage payments and can potentially accumulate more wealth over time. This can lead to greater retirement savings and financial security.
| Down Payment (%) | Mortgage Balance | Monthly Mortgage Payments | Retirement Savings |
|---|---|---|---|
| 20% | $400,000 | $1,875 | Higher |
| 10% | $450,000 | $2,250 | Lower |
Tax Benefits and Incentives for Down Payment Savings
Tax-advantaged accounts like 401(k), IRA, and Roth IRA can significantly contribute to down payment savings. These accounts are designed to encourage saving for retirement, but they can also be used to build a down payment fund for a home. By utilizing tax-advantaged accounts, individuals can reduce their taxable income, lower their tax burden, and potentially increase their savings.Understanding Tax-Advantaged Accounts
Tax-advantaged accounts, such as 401(k) and IRA, offer a tax-deferred growth of investments, which means that the earnings on the investments are not subject to income tax until they are withdrawn. This can result in significant tax savings over time. For example, if an individual contributes $5,000 to a 401(k) account and earns a 7% return, they will have $5,500 (including the $5,000 contribution) in the account after one year. However, the earnings of $500 will not be subject to income tax until withdrawal, reducing the individual's taxable income.- Contribution Limits: Tax-advantaged accounts have contribution limits that vary by year and account type. In 2022, the annual contribution limit for 401(k) and IRA accounts was $19,500.
- Tax Benefits: Tax-advantaged accounts offer tax benefits, such as deducting contributions from taxable income, which can reduce the individual's taxable income and lower their tax liability.
- Investment Options: Tax-advantaged accounts typically offer a range of investment options, which can be used to grow the account balance over time.
Tax Credits and Deductions for Homebuyers
The federal government and many states offer tax credits and deductions to help homebuyers with down payment savings. These incentives can be used in conjunction with tax-advantaged accounts to further reduce the financial burden of buying a home.- Federal Tax Credits: The federal government offers tax credits for first-time homebuyers, such as the Mortgage Credit Certificate (MCC) program, which allows homebuyers to claim a tax credit for a portion of their mortgage interest payment.
- State Tax Credits: Many states offer tax credits for homebuyers, such as the California Homebuyer's Downpayment Assistance Program, which provides a tax credit for homebuyers who purchase a home in a targeted area.
- Tax Deductions: The IRS allows homebuyers to deduct mortgage interest and property taxes from their taxable income, which can reduce their tax liability.
Carefully Consider Tax Implications
When deciding on a down payment strategy, it's essential to consider the tax implications of your choices. By utilizing tax-advantaged accounts, tax credits, and deductions, homebuyers can potentially save thousands of dollars in taxes and reduce the financial burden of buying a home.- Consult a Tax Professional: To maximize tax benefits and minimize tax liabilities, it's essential to consult with a tax professional who can provide guidance on the best tax strategy for your situation.
- Tax Implications of Withdrawal: When withdrawing funds from a tax-advantaged account, it's essential to consider the tax implications of the withdrawal, as it may be subject to income tax and penalties.
- Strategic Planning: Careful planning can help minimize tax liabilities and maximize tax benefits, which can result in significant savings over time.
Outcome Summary
In conclusion, determining how much to put down on a house is a critical decision that requires careful consideration of various factors, including credit score, income, debt-to-income ratio, and personal financial goals. By understanding the importance of down payment and creating a well-planned savings strategy, individuals can secure their mortgage and future with confidence. It's also essential to explore down payment assistance programs and options, which can help make homeownership more accessible and affordable.
Popular Questions
What is the minimum down payment required for a mortgage?
The minimum down payment for a mortgage varies depending on the loan program and lender, but it's typically 3.5% to 5% of the purchase price.
Can I use gifts or assistance for my down payment?
Yes, you can use gifts or assistance for your down payment, but there may be restrictions and requirements, such as documenting the source of the funds and meeting specific income or credit score thresholds.
How does my credit score affect my down payment options?
Your credit score plays a significant role in determining your down payment options. A higher credit score can qualify you for better loan terms and lower mortgage insurance premiums.
Can I put down too much for a house?
Yes, putting down too much for a house can be risky, as you may end up tying up a large portion of your savings in the down payment, leaving you with limited financial flexibility.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of gifellowcasesubmission.olympusamerica.com.