Federal Retiree COLA 2026 A Vital Adjustment for Beneficiaries
Table of Contents
- Understanding Federal Retiree Cost-of-Living Adjustments
- History and Significance of COLA
- COLA Calculation Methods
- COLA Calculation Method vs. Other Groups
- Impact on Purchasing Power
- Examples of COLA Impact Over Time
- Factors Affecting Federal Retiree COLA in 2026: Federal Retiree Cola 2026
- The Impact of Inflation Rates on Federal Retiree COLA
- Economic Conditions and Federal Retiree COLA
- Government Policies and Federal Retiree COLA
- Demographic Trends and Federal Retiree COLA, Federal retiree cola 2026
- How to Determine Your 2026 Federal Retiree COLA
- Step 1: Gather Necessary Data
- Step 2: Use Online Tools or Software
- Formula and Calculation
- Tax Implications and Budgeting
- The Role of the Federal Employee Retirement System in COLA Determinations
- Structure and Goals of the Federal Employees Health Benefits (FEHB) Program
- Role of the Federal Employee Retirement System (FERS) in COLA Decisions
- Potential Impact of Changes in FERS and FEHB Policies on COLA Rates
- Implications of COLA on Federal Retiree Budgeting and Planning
- Risks Associated with COLA Changes
- Opportunities for Federal Retirees
- Strategies for Adapting to COLA Changes
- Preparing for Unexpected COLA Changes
- Outcome Summary
- User Queries
With federal retiree COLA 2026 at the forefront, federal retirees are eager to understand the upcoming changes to their cost-of-living adjustments (COLAs). These adjustments, which are typically determined by the Consumer Price Index (CPI) and other economic factors, play a significant role in the purchasing power of federal retirees. In this discussion, we will delve into the history and significance of federal retiree COLAs, as well as the factors and trends that impact their determination.
Understanding these factors will enable federal retirees to prepare for the possible changes in their COLAs and make informed decisions about their financial planning. Additionally, this discussion will explore the role of the Federal Employees Health Benefits (FEHB) program and the Federal Employee Retirement System (FERS) in determining COLAs. By the end of this article, readers will have a comprehensive understanding of the federal retiree COLA 2026 and its potential impact on their lives.
Understanding Federal Retiree Cost-of-Living Adjustments
The Cost-of-Living Adjustment (COLA) is a crucial component of the federal retiree benefit system, designed to protect the purchasing power of retirees from inflation. Introduced in 1972, the COLA ensures that the buying power of Social Security beneficiaries and other federal retirees keeps pace with the rising cost of living. This adjustment is particularly significant for federal retirees, who often live on a fixed income, making it essential to safeguard their standard of living.
History and Significance of COLA
The COLA was first implemented as part of the Social Security Act of 1972. The decision came in response to rising inflation, which eroded the purchasing power of Social Security beneficiaries and other retirees. Since then, the COLA has been adjusted annually, ensuring that the buying power of federal retirees keeps pace with inflation. Over time, the COLA has become an essential feature of the federal retiree benefit system, providing financial stability for millions of Americans.
COLA Calculation Methods
Federal retirees receive the same COLA calculation as Social Security beneficiaries. The COLA is calculated by the Bureau of Labor Statistics (BLS) and is typically released in October of each year. The calculation is based on the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W), which tracks the cost of living for urban wage earners and clerical workers. The BLS compares the CPI-W for the third quarter of the current year to the same period in the previous year, resulting in an increase or decrease in federal retirees' benefits.
COLA Calculation Method vs. Other Groups
One notable difference between COLA calculation for federal retirees and Social Security beneficiaries lies in the consumer price index used for COLA calculations. Social Security COLAs are primarily based on the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W). However, for some special minimum benefits, other consumer price indexes might be used, and for a few specific cases, a slightly alternative index might apply. For instance, a subset called the
CPI-E Index
or
Consumer Price Index for the Elderly (CPI-E)
tracks the expenses of people aged 62 and over.
Impact on Purchasing Power
The COLA has an immediate impact on federal retirees' purchasing power. A 1% increase in the COLA means a 1% increase in federal retirees' benefits. Over time, these increases add up, ensuring that retirees' buying power remains stable despite inflation. For example, between 1972 and 2022, a Social Security beneficiary who received $500 per month in 1972 would have seen their monthly benefit increase to approximately $3,800 by 2022, assuming a 1% annual COLA.
Examples of COLA Impact Over Time
A
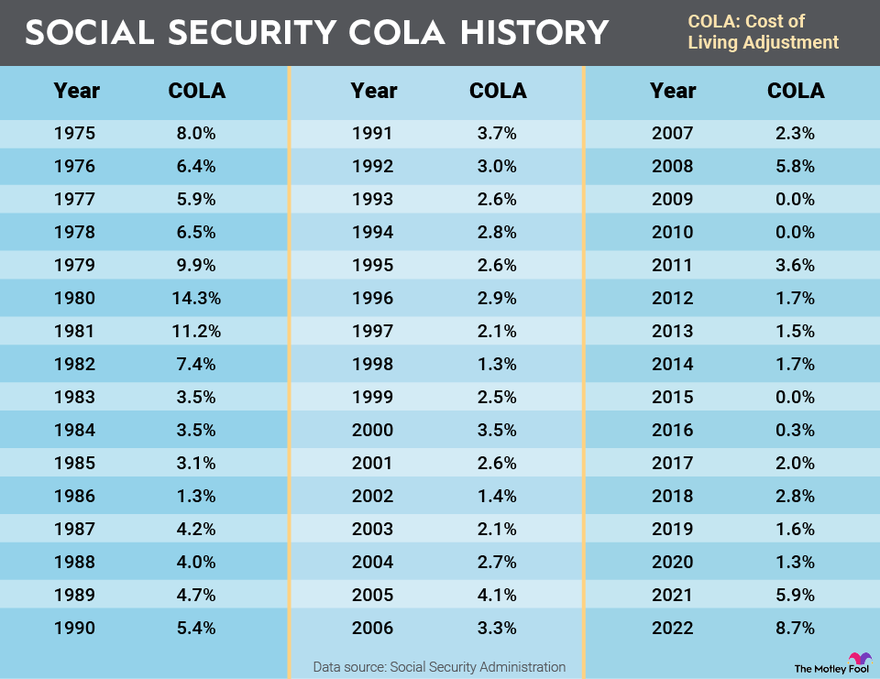

| Scenario | Potential Impact on COLA Rates |
|---|---|
| Change in CPI-W calculation methodology | Larger or smaller COLA adjustments for federal retirees |
| Shifts in the inflation rate | Changes in COLA rates based on the change in inflation rates |
| Adjustments in federal government spending | Changes in COLA rates based on changes in federal spending |
| Changes in health care costs | Changes in COLA rates based on changes in health care costs |
| Changes in FEHB policies | Changes in COLA rates based on changes in FEHB policies |
Implications of COLA on Federal Retiree Budgeting and Planning
Budgeting and planning play a crucial role in the financial security of federal retirees. The Cost-of-Living Adjustment (COLA) is a vital component of their financial strategy, as it directly affects their monthly retirement benefits. Understanding how COLA impacts federal retiree budgeting and planning is essential for making informed decisions about their financial future.Risks Associated with COLA Changes
Changes in COLA rates can have both positive and negative effects on federal retirees' budgets and financial plans.- Increased expenses: Higher COLA rates may lead to increased expenses, especially if retirees are expecting a smaller increase in their benefits. This can put a strain on their budget and force them to reevaluate their financial priorities.
- Budget adjustments: Federal retirees must adjust their budgets accordingly when COLA rates increase, which can be challenging, especially for those with fixed incomes.
- Opportunity to reevaluate expenses: On the other hand, a higher COLA rate can also present an opportunity for federal retirees to reevaluate their expenses and adjust their budget to take advantage of the increased purchasing power.
- Rising medical expenses: COLA changes can also impact medical expenses, which can be a significant challenge for federal retirees with ongoing medical needs.
Opportunities for Federal Retirees
While COLA changes can be unpredictable, they also present opportunities for federal retirees to adjust their budgets and financial plans.- Increased purchasing power: Higher COLA rates can increase the purchasing power of federal retirees, allowing them to afford more goods and services.
- Adjusting expenses: With increased COLA rates, federal retirees can adjust their expenses to take advantage of the increased purchasing power and improve their overall quality of life.
- Increased tax credits and deductions: Federal retirees may also be eligible for increased tax credits and deductions, which can help reduce their tax liability and increase their disposable income.
- Strategic investing: Higher COLA rates can also present opportunities for strategic investing, allowing federal retirees to adjust their investment portfolios and take advantage of increased market volatility.
Strategies for Adapting to COLA Changes
To adapt to COLA changes, federal retirees can implement the following strategies:- Review and adjust budget: Regularly review and adjust their budget to take into account changes in COLA rates and other expenses.
- Monitor expenses: Federal retirees should monitor their expenses closely to identify areas where they can cut back and allocate their increased purchasing power more effectively.
- Diversify investments: Diversify their investment portfolios to take advantage of increased market volatility and reduce their risk exposure.
- Consult with a financial advisor: Consult with a financial advisor to develop a customized financial plan that addresses their unique needs and goals.
Preparing for Unexpected COLA Changes
While COLA changes can be unpredictable, federal retirees can prepare for unexpected changes by having a plan in place.- Emergency fund: Maintain an emergency fund to cover unexpected expenses and provide a cushion for sudden changes in COLA rates.
- Flexibility: Federal retirees should maintain a degree of flexibility in their budget and financial plans to accommodate unexpected changes in COLA rates.
- Adaptable investment strategy: Develop an adaptable investment strategy that can adjust to changing market conditions and COLA rates.
- Regular financial reviews: Regularly review their finances and make adjustments as needed to ensure they are prepared for unexpected COLA changes.
Outcome Summary
To summarize, federal retiree COLA 2026 is a crucial adjustment that will significantly impact the purchasing power of federal retirees. Understanding the factors and trends that influence this adjustment is essential for making informed financial decisions. By preparing for the potential changes in their COLAs, federal retirees can ensure a comfortable and secure retirement. Whether they are approaching retirement or have already begun their post-federal career, this discussion has provided valuable insights into the world of federal retiree COLAs.
User Queries
Q: What is a Cost-of-Living Adjustment (COLA)?
A: A Cost-of-Living Adjustment (COLA) is a change to an employee's or retiree's salary, benefit, or pension to keep pace with inflation and preserve their purchasing power.
Q: How is a COLA calculated for federal retirees?
A: A COLA for federal retirees is typically calculated based on the Consumer Price Index (CPI) or other economic factors, which measure the rate of inflation and changes in the cost of goods and services.
Q: Why is COLA important for federal retirees?
A: COLA is essential for federal retirees because it helps maintain their purchasing power, ensuring they can afford to maintain their standard of living in retirement. A COLA adjustment allows federal retirees to adjust to changes in the cost of living and maintain the value of their retirement benefits.
Q: Can federal retirees influence the COLA determination?
A: While federal retirees cannot directly influence the COLA determination, they can participate in the process by providing feedback and suggestions to their representatives and policymakers. Advocating for their interests and needs helps shape the government's policies and decisions regarding COLAs.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of gifellowcasesubmission.olympusamerica.com.