Advance Premium Tax Credit 2026 Maximizing Benefits
Table of Contents
- Understanding the Advance Premium Tax Credit (APTC) 2026 Eligibility Requirements
- Income Limits for APTC Eligibility in 2026
- Importance of Verifying Family Size and Income
- Determining Household Income for APTC Purposes
- Determining Household Size for APTC Purposes
- Documenting Income and Family Size for APTC Application
- How APTC Affects Premiums and Cost-Burden for Low-Income Households
- Calculating the APTC Premium Amount
- The Impact of APTC on Reducing Cost Burden, Advance premium tax credit 2026
- The Subsidy Cliff and Its Effects on APTC
- Changes to APTC in the American Rescue Plan Act (ARPA) 2026
- Increased Maximum APTC Amount
- Expanded Eligibility for APTC
- No APTC Reconciliation Required
- Increased Funding for Premium Assistance
- Broadened Definition of Dependents
- Maximizing APTC Benefits for Special Populations in 2026
- Native American Populations
- Individuals with Disabilities
- Individuals Experiencing Unemployment or Poverty
- Special Accommodations and Resources
- Conclusive Thoughts: Advance Premium Tax Credit 2026
- Detailed FAQs
Kicking off with advance premium tax credit 2026, this opening paragraph is designed to captivate and engage the readers, setting the stage for an in-depth analysis of this crucial tax credit. As a vital component of the Affordable Care Act, advance premium tax credit 2026 plays a key role in mitigating the financial burden of healthcare for low-to-middle-income families. The credit can significantly reduce the cost of health insurance premiums, making it more accessible and affordable for individuals and families who need it most.
In 2026, the advance premium tax credit is expected to undergo significant changes, expanding its reach and benefits. To qualify for this tax credit, individuals and families must meet specific income and eligibility requirements, which can vary depending on family size. Understanding the intricacies of the advance premium tax credit 2026 is essential for maximizing its benefits and taking advantage of the available subsidies.
Understanding the Advance Premium Tax Credit (APTC) 2026 Eligibility Requirements
To understand the eligibility requirements for the Advance Premium Tax Credit (APTC) in 2026, it is essential to grasp the income limits that apply to different family sizes. The APTC program aims to assist individuals and families in obtaining affordable health insurance by providing a reimbursement for the premiums paid on the selected plan. Eligibility for APTC is contingent upon meeting certain income and family size requirements.
Income Limits for APTC Eligibility in 2026
The income limits for APTC eligibility in 2026 vary based on the family size. The Centers for Medicare and Medicaid Services (CMS) publishes these income limits annually. For the 2026 tax year, the income limits are as follows:
- Families of four with an income up to 300% of the Federal Poverty Level (FPL) are eligible for APTC. This translates to a maximum annual income of $76,560, based on the 2026 FPL.
- Families of three with an income up to 300% of the FPL have a maximum annual income of $65,440.
- Families of two with an income up to 300% of the FPL have a maximum annual income of $54,360.
- Individuals with an income up to 300% of the FPL have a maximum annual income of $38,640.
The income limits are determined by the household's gross income, which includes wages, salaries, and other forms of income. However, these limits do not apply to families with qualifying children under the age of 19, as their income is considered when determining the family size.
Importance of Verifying Family Size and Income
Accurate family size and income information are crucial when applying for APTC. The Marketplace uses this information to determine the eligible plan levels and the amount of the APTC subsidy. Inaccurate or incomplete information may result in an incorrect APTC amount, which can lead to additional taxes owed when filing the tax return or reduced benefits. Therefore, applicants must ensure the accuracy of their information when applying for APTC.
Determining Household Income for APTC Purposes
To determine the household income for APTC purposes, the Marketplace considers all forms of income received by all household members. This includes but is not limited to:
* Wages and salaries
The Marketplace does not consider certain types of income, such as:
Food stampsDetermining Household Size for APTC Purposes
When determining household size for APTC purposes, the Marketplace considers the number of individuals in the household who are:In cases where there are multiple family units living in the same household, the Marketplace considers each family unit separately. For example, two single-parent households living together are considered two separate households.
Documenting Income and Family Size for APTC Application
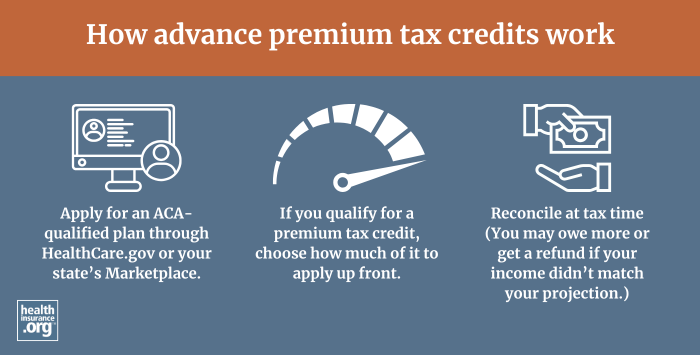
Applicants must provide documentation to support their income and family size claims when applying for APTC on healthcare.gov or through the Marketplace. This documentation typically includes:* Tax returns (previous year's tax return and current year's income statement)
Applicants should ensure they have the necessary documentation before submitting their application to avoid delays in the APTC approval process.
How APTC Affects Premiums and Cost-Burden for Low-Income Households

Calculating the APTC Premium Amount
The APTC premium amount is calculated based on the following steps:Step 1: Determine Your Modified Adjusted Gross Income (MAGI) Your MAGI is your adjusted gross income (AGI) from your tax return, minus certain deductions and additions, such as student loan interest and alimony payments.
Step 2: Determine Your Family Size Your family size includes yourself, your spouse, and any dependents.
Step 3: Apply the APTC Percentage to Your MAGI and Family Size The APTC percentage varies based on your MAGI and family size. The APTC percentage ranges from 0% to 9.83%.
Step 4: Calculate Your APTC Amount Multiply your MAGI by the applicable APTC percentage to determine your APTC amount.
For example, if your MAGI is $20,000 and your APTC percentage is 6.41%, your APTC amount would be $1,282.00.
The Impact of APTC on Reducing Cost Burden, Advance premium tax credit 2026
The APTC has a significant impact on reducing the cost burden for low-income households. By providing subsidies to qualified individuals and families, the APTC helps make health insurance more affordable.The Subsidy Cliff and Its Effects on APTC
The subsidy cliff refers to the sudden and significant reduction in subsidies when income increases, even by a small amount. This can lead to a significant increase in health insurance premiums, making health insurance unaffordable for some individuals and families.For example, if an individual's income increases from $20,000 to $21,000, their APTC amount may decrease significantly, resulting in a subsidy cliff. This can lead to a significant increase in health insurance premiums, making it difficult for the individual to afford health insurance.
The subsidy cliff can have a significant impact on low-income households, making it difficult for them to afford health insurance.In conclusion, the APTC plays a crucial role in reducing the financial burden of health insurance premiums for low-income households. By understanding how the APTC premium amount is calculated and the impact of the subsidy cliff, individuals and families can make informed decisions about their health insurance options.
Changes to APTC in the American Rescue Plan Act (ARPA) 2026
In the ARPA, the maximum APTC amount is increased from 8.05% of the national average premium to 8.5% for individuals and 9.83% for families. This change is expected to reduce the cost burden for low-income households and encourage more people to enroll in health insurance plans.
Increased Maximum APTC Amount
The ARPA raises the maximum APTC amount to 8.5% of the national average premium for individuals and 9.83% for families. This increase in the maximum APTC amount can result in lower premiums for those who qualify.- The new maximum APTC amount for individuals is 8.5% of the national average premium
- The new maximum APTC amount for families is 9.83% of the national average premium
Expanded Eligibility for APTC
The ARPA also expands the eligibility criteria for APTC, allowing more people to qualify for this credit. This expansion includes increasing the income limits for APTC eligibility.- The ARPA increases the income limits for APTC eligibility, allowing more people to qualify
- The new income limits for APTC eligibility are based on the federal poverty level (FPL)
No APTC Reconciliation Required
The ARPA eliminates the requirement for individuals to reconcile their APTC with their actual premium payments. This change simplifies the APTC process and eliminates the risk of paying back excess APTC.- Individuals are no longer required to reconcile their APTC with their actual premium payments
- This change eliminates the risk of paying back excess APTC
Increased Funding for Premium Assistance
The ARPA provides increased funding for premium assistance programs, including APTC. This additional funding allows for more people to receive premium assistance and reduces the cost burden for low-income households.- The ARPA provides increased funding for premium assistance programs, including APTC
- This additional funding allows for more people to receive premium assistance
Broadened Definition of Dependents
The ARPA broadens the definition of dependents for APTC purposes. This change allows more individuals to qualify as dependents and receive premium assistance.- The ARPA broadens the definition of dependents for APTC purposes
- This change allows more individuals to qualify as dependents and receive premium assistance
The ARPA's changes to APTC aim to make health insurance more affordable for low-income households and encourage more people to enroll in health insurance plans.
Maximizing APTC Benefits for Special Populations in 2026
Native American Populations
Native American populations are eligible for APTC benefits, but they must meet specific requirements. These requirements include:- Enrollment in a qualified health plan through the Health Insurance Marketplace.
- Residency on a reservation or trust land, or membership in a federally recognized tribe.
- Income at or below 138% of the federal poverty level.
Individuals with Disabilities
Individuals with disabilities may be eligible for APTC benefits, but they must meet specific criteria. This includes:- Enrollment in a qualified health plan through the Health Insurance Marketplace.
- Income at or below 138% of the federal poverty level.
- Receipt of a disability benefit from the Social Security Administration (SSA) or other disability programs.
Individuals Experiencing Unemployment or Poverty
Individuals experiencing unemployment or poverty may be eligible for APTC benefits. To apply for APTC, these individuals must:- Enroll in a qualified health plan through the Health Insurance Marketplace.
- Provide documentation of their income and household size.
- Complete an application for APTC through the Health Insurance Marketplace.
Special Accommodations and Resources
Special accommodations and resources are available for individuals with disabilities and those experiencing unemployment or poverty. These resources include:- Telehealth services: Many healthcare providers offer telehealth services, which can provide convenient and accessible healthcare for individuals with disabilities.
- Healthcare assistance programs: Programs such as Medicaid and the Children's Health Insurance Program (CHIP) may be available to individuals with disabilities and those experiencing unemployment or poverty.
The APTC can play a critical role in reducing healthcare costs for special populations in 2026. By understanding the specific requirements for eligibility and the application process, these populations can access affordable health insurance coverage and improve their overall health outcomes.
- Special accommodations and resources are available for individuals with disabilities and those experiencing unemployment or poverty.
- The APTC application process involves assessing the individual's income and household size.
- Telehealth services and healthcare assistance programs may be available to qualified individuals.
Conclusive Thoughts: Advance Premium Tax Credit 2026
In conclusion, the advance premium tax credit 2026 is a vital tool in ensuring that healthcare is affordable and accessible to all. By understanding the eligibility requirements, factors affecting the amount of credit received, and the impact of the credit on premiums and cost-burden, individuals and families can make informed decisions about their healthcare needs. As the tax credit continues to evolve, it's essential to stay up-to-date on the latest changes and modifications to maximize its benefits.
Detailed FAQs
What is the maximum income limit for advance premium tax credit 2026?
The maximum income limit for advance premium tax credit 2026 varies depending on family size. For a family of four, the maximum income limit is approximately $50,000.
How do I apply for advance premium tax credit 2026?
To apply for advance premium tax credit 2026, you can visit the official HealthCare.gov website or contact a licensed health insurance broker. You must provide documentation of your income and family size to qualify for the credit.
Can I switch between health insurance plans without affecting my advance premium tax credit 2026?
Yes, you can switch between health insurance plans, but it may affect your advance premium tax credit 2026. You must notify the Health Insurance Marketplace of any changes to your coverage, and you may need to reapply for the credit.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of gifellowcasesubmission.olympusamerica.com.